

Don Wright has served at the Deputy Minister level in the Saskatchewan and British Columbia governments. He currently serves as a Fellow with the Public Policy Forum, a Senior Fellow with the C.D. Howe Institute, and Senior Counsel with Global Public Affairs.
In 1995 the Canadian economy was not exactly humming along – it still hadn’t got its mojo back after the severe 1990-92 recession. The unemployment rate was 9.5%, GDP per capita had only just made it back to the level of 1989, and steep spending cuts in Paul Martin’s February budget signaled more contraction.
That was the context when Prime Minister Chrétien made Natural Resources Minister Anne McLellan the point person to work with the Alberta government and the oil industry to accelerate development of the oil sands, which had been stuck at two plants for nearly two decades. In its 1996 budget the federal government granted oil sands developers accelerated capital cost allowances. The Alberta government made complementary changes in its royalty structure. In June of that year Chrétien and McLellan went to Fort McMurray to sign the “Declaration of Opportunity” – a federal-provincial agreement codifying all of this.
The results were dramatic. From 1996 to 2015 capital investment in the oil sands was more than $360 billion (in 2025 dollars). The increase in oil sands investment accounted for 28% of the total increase in total Canadian non-residential investment over those years. Oil sands production grew from 430,000 barrels per day in 1995 to 2.38 million in 2015 to 3.5 million in 2025.
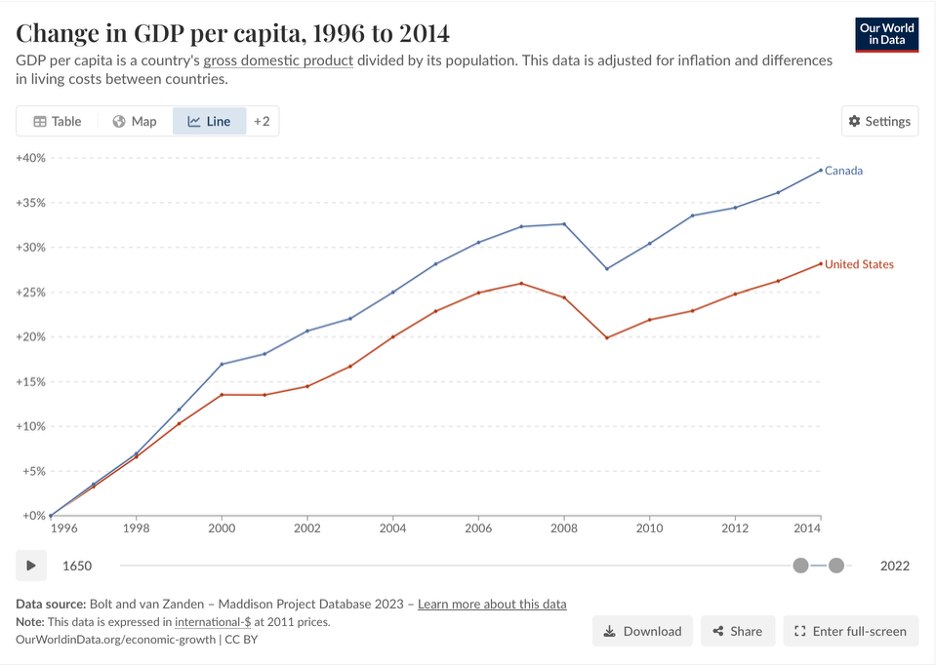
Canada’s overall economic and fiscal performance improved dramatically after 1995. The unemployment rate fell from 9.5% in 1995 to 6.2% in 2007, just before the Great Financial Crisis (GFC). Over the same period Canadians experienced the first decent growth in per capita GDP since the 1970s. The Canadian economy recovered from the GFC much more quickly than the U.S. economy. Figure 1 below shows growth in GDP per capita from 1996 to 2014 - the only period since the 1970’s in which Canada’s growth exceeded that of the U.S.
Figure 1 - % Growth in GDP per Capita, Canada and the United States, 1996-2014
This also contributed to Paul Martin’s success in eliminating the federal deficit – his spending restraint was more than offset by the revenue growth thrown off by a relatively rapidly growing economy.
While the investment in the oil sands was not the only contributor to the turnaround in Canada’s economic and fiscal performance, it was surely a significant factor.
History Rhymes
There are clear parallels between Canada’s circumstances 30 years ago and today. Canada’s economic performance – particularly in per capita terms – has been very poor for most of the past 10 years, even before the challenges presented by Trump II. Echoing Jean Chrétien, Prime Minister Carney has apparently concluded that expansion of Alberta’s energy sector must play a significant role in kick-starting the Canadian economy into higher gear. Thus, the current version of the declaration of opportunity – the Canada-Alberta MOU, and now what appears to be a complementary Canada-B.C. MOU as well.
There are many issues to interrogate with respect to the pros and cons of the Canada-Alberta MOU. In this piece I want to focus on one question: who will benefit if the MOU results in a significant expansion of Alberta’s energy sector? Many opponents of the federal government’s decision to sign the MOU suggest it represents a major concession to Alberta, implying that Alberta will be the major beneficiary of an expansion of its energy sector, and other parts of Canada will benefit little, or may even bear net costs.1
This type of thinking was foreign to Jean Chrétien. Referencing the agreement with Alberta in debate in the House of Commons in 1996, he stated: “That is what Canada is about. It means being able to find what works in each part of the country so that everyone can benefit. If the oil companies make money in Alberta, they pay taxes to the central government, which redistributes the money to all Canadian provinces.”
Was Prime Minister Chrétien correct in stating that the expansion was good for all Canadians? Let’s look at what the data says.
How Fiscal Federalism Works in Canada
Finances of the Nation (FOTN) is a wonderful resource of Canadian public finance data put together by a group of economists and some fellow travellers of the dismal science. It has a data series entitled “Federal Fiscal Balance” which shows federal government revenue and expenditures by province. The difference between the revenue collected from taxpayers in any province and the expenditure in that province is deemed to be that province’s federal fiscal balance. If that balance is positive, it means the federal government collects more revenue in that province than it spends in that province.
Figure 2 below shows what those balances looked like in 1995. The balances are shown in 2022 dollars, so that the impact of inflation is taken out when we compare 1995 to subsequent years.
Figure 2 – Federal Government Fiscal Balance by Province and Territories, 1995
($ 2022 Millions)
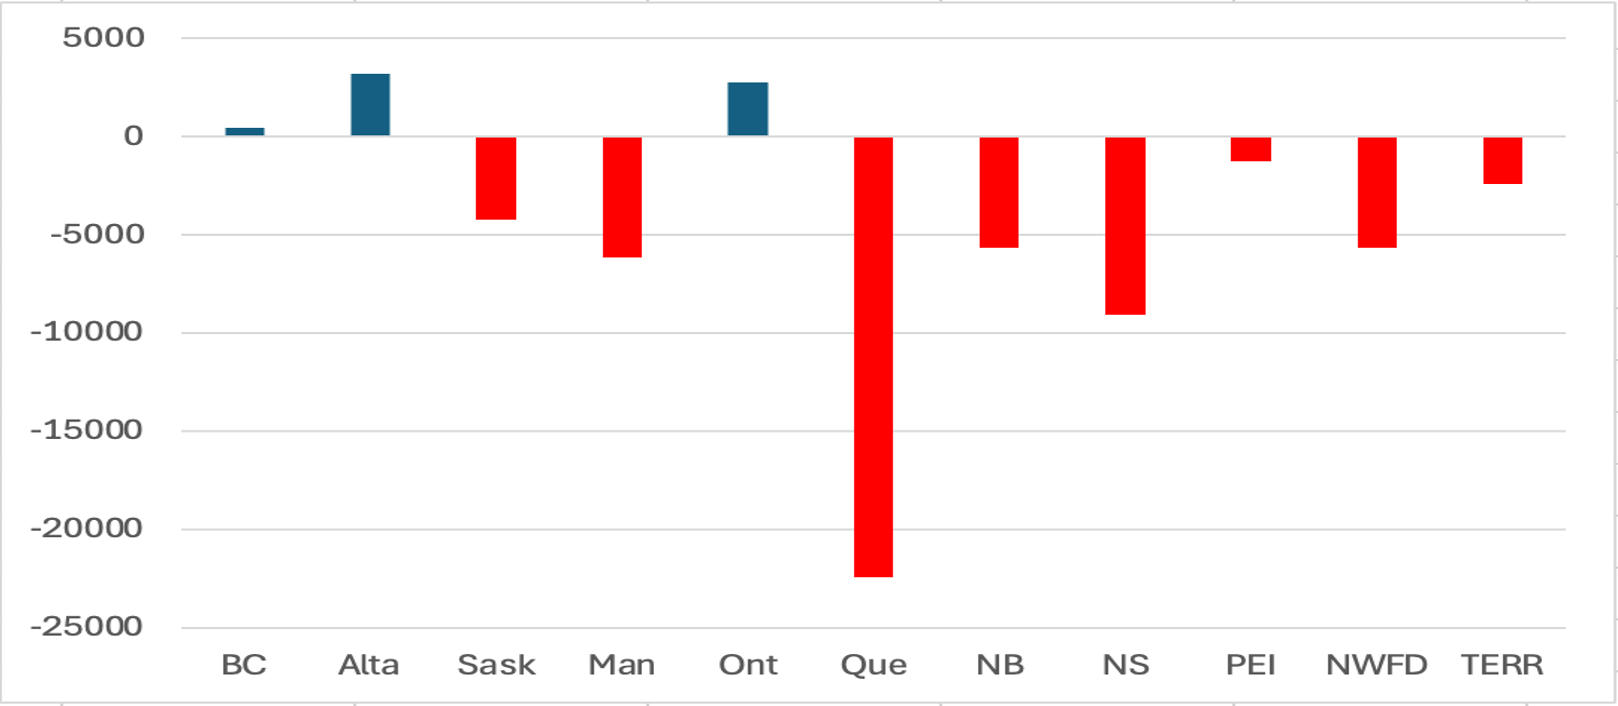
In 1995 there were only three provinces – British Columbia, Alberta and Ontario – that had positive balances. Alberta’s balance was the largest at $3.2 billion.
Before moving on it is important to clarify what this positive balance does not represent. It does not show that Canadian federalism is tilted against Alberta. Rather it is a natural outcome of the incidence of federal taxation and spending. A few examples of how this works:
The government collects proportionately more revenue from higher income people; average incomes are higher in Alberta than in the rest of Canada.
Unemployment insurance goes disproportionately to provinces with high unemployment rates; Alberta has lower unemployment rates than the average in the rest of Canada.
Payments to seniors are a significant proportion of federal expenditures; Alberta’s seniors represent a smaller proportion of its population than in the rest of the country.
Equalization payments are explicitly designed to equalize per capita revenue capacity across provinces; Alberta was a net recipient of equalization from 1957-64, but not since then as its per capita revenue capacity has become the highest amongst all the provinces.
How Did the Picture Change Between 1995 and 2025?
Between 1995 and 2025 real GDP grew by 23% more in Alberta than it did in the rest of Canada. The primary driver of this was the significant increase in investment in the oil sands and the 8-fold increase in oil sand production stated above. It is important to note that economic growth in the rest of Canada was itself stimulated by the investment in the oil sands as Canadian suppliers outside Alberta saw an increase in demand for their products.
Of particular interest here is how this impacted the federal-provincial fiscal balance. Figure 3 below compares how Alberta’s balance changed between 1995 and 2024 (the last year for which the FOTN data is available.)
Figure 3 - Federal Government Fiscal Balance Alberta, 1995-2024
($ 2022 Millions)
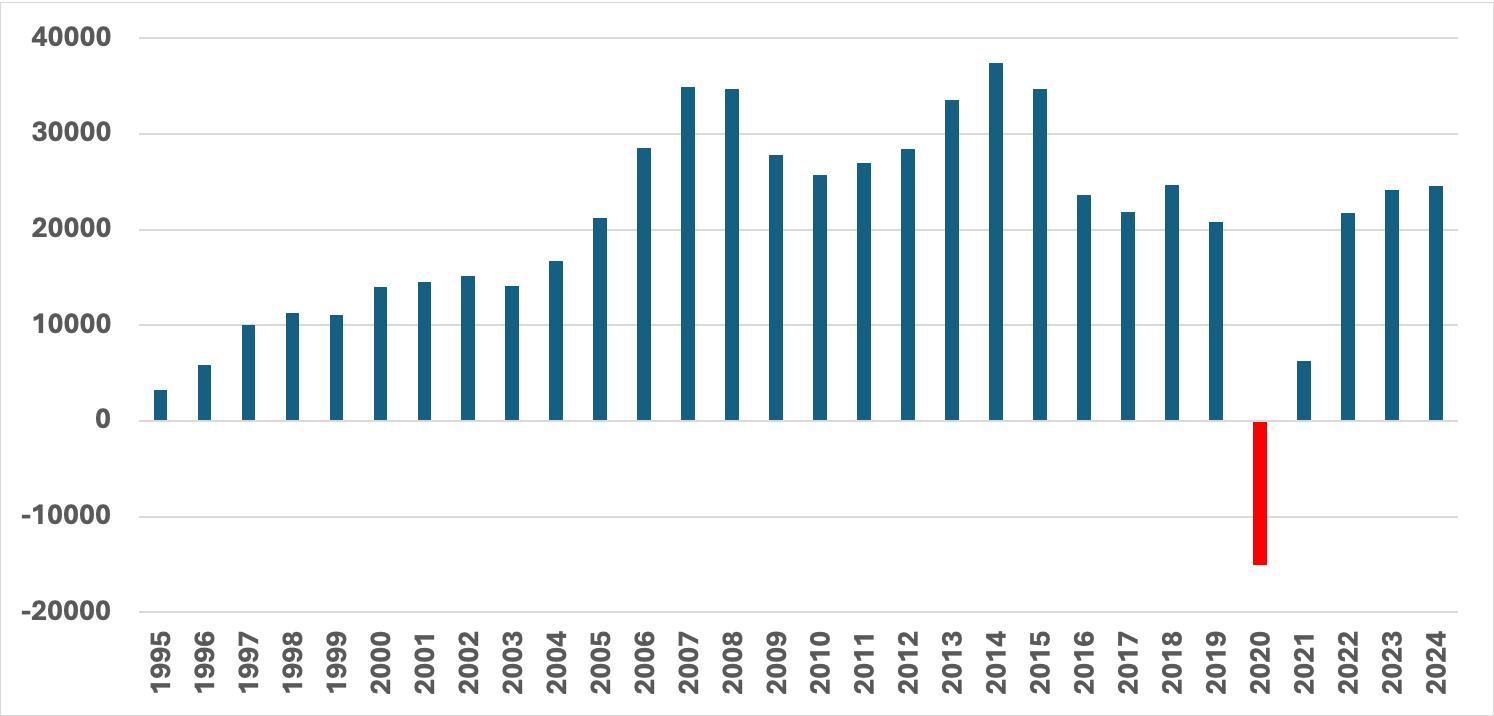
The general trend of Alberta’s positive fiscal balance with the federal government was up from 1995 to 2024 - rising from $3.2 billion in 1995 to $24.6 billion in 2024. The temporary peaks around 2007-08 and 2013-14 reflected unusually high oil prices – the WTI price averaged $US100 per barrel in 2008 and $US98 in 2013. 2020 and 2021 were anomalous years because of the unprecedented rise in the level of federal spending during the COVID pandemic – the net fiscal balance for all provinces and territories was negative $211.7 billion in 2020 and negative $76.8 billion in 2021.
Amongst the other provinces, only British Columbia and Newfoundland and Labrador saw a net positive change in their balances. (In Newfoundland and Labrador’s case its negative balance became smaller over the period.) Even traditionally “rich” Ontario saw a negative swing in its balance. Figure 4 below compares the federal fiscal balance for Alberta and the aggregate balance of all the other provinces and territories over the same period. I have left out 2020 and 2021 simply to avoid swamping the scale of the vertical axis.
Figure 4 – Federal Government Balance, Alberta and the Rest of Canada, 1995-2024
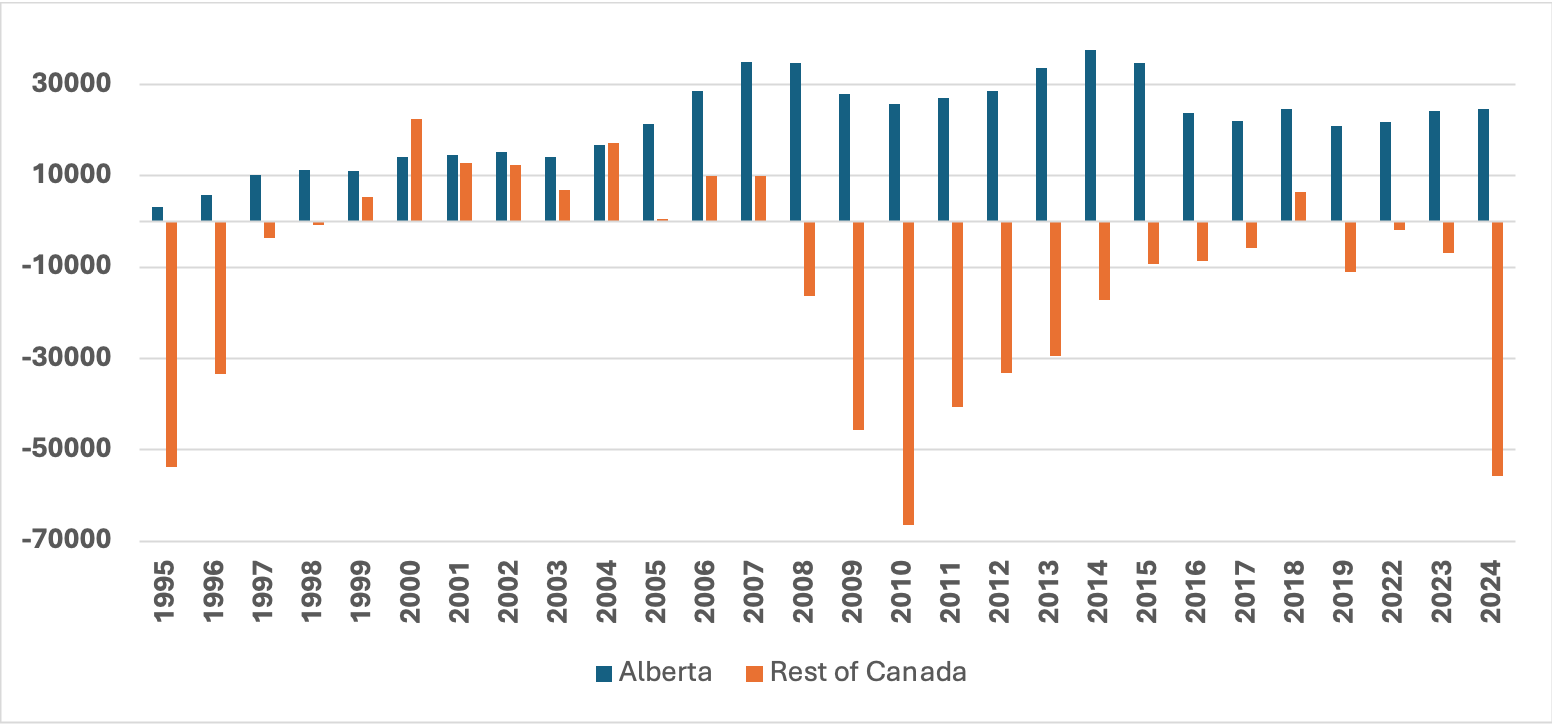
In contrast to the general upwards trend of Alberta’s balance, the aggregate balance for the other provinces cycled up and down with no discernible trend.
To provide an order-of-magnitude estimate of what Alberta’s growing contribution, driven by the investment in expanding oil sands production, meant to the rest of Canada, I calculated a simple counterfactual based on the following assumptions:
Alberta’s net fiscal balance would only increase after 1995 at the rate of inflation;
The federal government would not reduce expenditures to make up for Alberta’s lower net fiscal balance, but would rather increase its deficit, or reduce its surplus2 in any year;
The rate of interest paid on the increase in debt resulting from this would be 3%.3
In this scenario the federal government’s debt in 2024 would have been $590 billion higher than its actual level - $1,060 billion.4 Certainly, a material difference.
Now, I would hope that under this scenario the federal government would not have just mindlessly run up the national debt – that it would have shown some measure of fiscal prudence and dialed back spending and/or raised taxes. But that stark figure - $590 billion – does provide a sense of the costs the rest of the country would have borne – either through spending cuts, higher taxes or reduced fiscal capacity to meet the nation’s future needs - if Alberta’s energy sector had not expanded the way it did after 1995.
“A billion here, a billion there, and pretty soon you are talking real money.5 It would seem that Mr. Chrétien’s prediction in 1996 has been borne out. The expansion of Alberta’s energy sector has paid, and continues to pay, substantial dividends to the rest of the country.
Some Final Words (For Now)
Let me say again that none of this is proof that the Canada’s federal bargain is tilted against Alberta. It is important to remember that the federal government supported the expansion of the oil sands through favourable taxation changes. Before that, in 1975 Canada prevented the collapse of the Syncrude project by taking an equity stake in it when one of its private partners pulled the plug on its participation. And going further back, the 1961 National Oil Policy required all regions west of the Ottawa Valley to use only Canadian – primarily Albertan – oil. At that time, the Canadian price exceeded the international price. This provided the platform for the expansion of Alberta’s oil industry and its current high per revenue capacity. More recently, the federal government’s takeover and completion of the TMX project allowed for significant increases in offshore exports of Alberta oil.
On the other hand, various voices outside of Alberta should dial down their demonization of Alberta and its energy sector and the arguments against “concessions” to Alberta. All of Canada has benefited significantly from the expansion of Alberta’s oil sand production since 1995. If there is an economic case for further expansion, and the additional pipeline capacity that would be needed to support it, all of Canada will share in the benefits if it can be made to happen.6
Canada would work so much better if we focused more of our attention on baking a bigger pie, rather than arguing over whose slice is too big and whose is too small. Something that Jean Chrétien fully understood in 1996 – and Mark Carney seems to understand exactly 30 years later.
If you liked this, you may also like:


See, for example, https://thewalrus.ca/alberta-bc-pipeline/
Although it may seem like a distant memory now, Canada ran budget surpluses from 1997 to 2008.
The arithmetic average of 3-year Canada bond yields over the 1995-2024 period was 3.03%.
https://www150.statcan.gc.ca/n1/daily-quotidien/251121/dq251121b-eng.htm
When U.S Senator Everett Dirksen made this statement in 1969, a US$ billion was worth about 6.7 times as much as it is today. Notwithstanding that, the basic sentiment still rings true.
The question of whether there is an economic case for further expansion of oil sands production certainly warrants further discussion. Before we get to that, I thought it was essential to clear away the dog-in-the-manger problem first.
I never bought into the green demand that we must end fossil fuel extraction yesterday. I think it’s wishful thinking. A well-planned transition to electric makes more sense to me, where oil & gas play a role while we develop our rare earth resources and energy infrastructure.
1) it would have been informative to see figure three replicated with 2025 data for a better apples to apples comparison.
2) I think that Carney realizes, unlike his predecessor, that the goal of mitigating the climate problem is a) not something with a short/term solution and b) not without significant costs that are outside the economies current capacity.
Goals set by passionate believers are great, they created both needed focus and urgency, but they are rarely achievable without some realignment.
The climate transition we need will not occur in 10 or even 25 years, this is a 75 to 100 year project which will require oil, gas, coal etc as we move to renewables, hydrogen, fusion.
I have no doubt we will get to a closer to neutral carbon footprint but $$ and time are required.
I also think it is extremely arrogant to assume that we will have full control over what the earth itself will do.
Thank you for the insights.